

What is a Registered Disability Savings Plan (RDSP)?
Who can open an RDSP?
- An adult beneficiaryⓘ who has the capacity to manage their own affairs
- The legal guardian of property of the beneficiary
- A parent or other qualifying family member of the beneficiary
For a beneficiary who is a minor, either a parent, both parents or a legal guardian of property can open and direct the RDSP. When the beneficiary reaches the age of majority, if they have the capacity to manage their own affairs, the beneficiary may take over as sole holder of the RDSP or be added as a joint holder.
A beneficiary can only have one RDSP at a time, except when transferring from one RDSP to a new one before discontinuing the old one.ⓘ
RDSP key numbers
$200,000
RDSP lifetime contribution limit, with no annual contribution limit (contributions are not tax-deductible)
59 years old
Maximum age a beneficiary can be during the calendar year when opening or contributingⓘ to an RDSP
$90,000
Maximum amount of disability grants and bonds that can be received into an RDSPⓘ
$70,000
Maximum for Canada Disability Savings Grant
$20,000
Maximum for Canada Disability Savings Bond
Explore how an RDSP works with government support
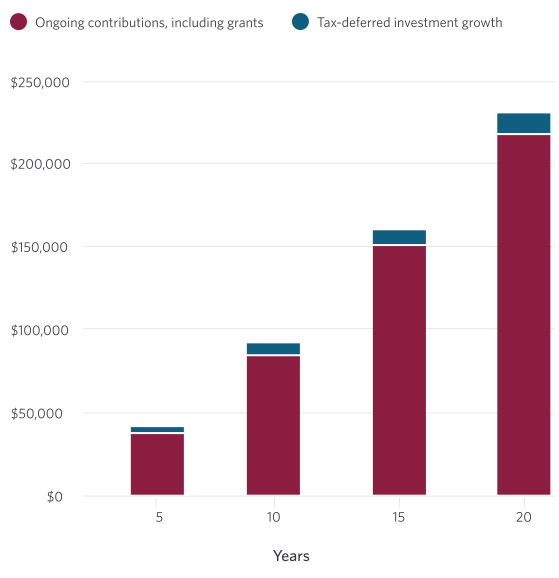
Alex
$90,000
Lives independently
$3,500
$292 monthly
Medium 5.8%

Alex's projected investment growth
20 years
$70,080
$70,000
$251,866
After investment growth

Money held in an RDSP account does not affect eligibility for provincial benefits.
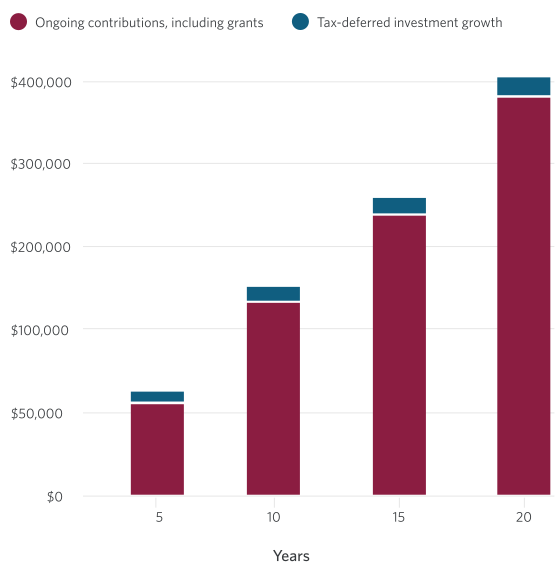
Sophia
$115,000
Lives in a family household
$1,000
$833 monthly
Medium 5.8%
Sophia's projected investment growth
20 years
$200,000
$20,000
$327,558
After investment growth
Money held in an RDSP account does not affect eligibility for provincial benefits.
Find the right investments for your RDSP
GICs
Get 100% of your original investment back, plus the interest you earned at the end of the term.
Mutual Funds
Choose professionally managed funds designed to help build long-term wealth.
Portfolio Solutions
Enjoy an all-in-one investment solution managed by a team of experts.
CIBC Personal Portfolio Solutions
Learn more about RDSPs and accessibility at CIBC
Buying or renting a home
Let’s talk about: RDSPs
A Registered Disability Savings Plan can help you secure your long-term financial future.
Buying or renting a home
Accessibility at CIBC
We’re committed to making sure our products and services are accessible to all our clients.
Buying or renting a home
Our Accessibility Plan
Explore our comprehensive strategy to prevent and remove barriers to accessibility.
Registered Disability Savings Plan (RDSP) FAQ
Ready to invest in an RDSP?
Create an investment plan with help from an advisor
- Connect with an experienced advisor who supports your needs and understands your unique priorities
- Explore investment options and opportunities with your advisor to help build your successful portfolio
- Book an appointment easily online, by phone or in person
Connect with a Registered Disability Savings Plan Advisor
- Get expert guidance and recommendations from our dedicated advisors who can share their expertise on registered disability savings plans
- Benefit from tailored advice based on your unique needs and goals
- Let us reach out to you directly to provide support